
The Instruments | Credit Union Financing
Credit Union Multiplex Financing in BC
For two years after Bill 44, BC homeowners could legally build a fourplex on their lot but could not walk into a lender and ask for a loan designed to do it. The product that filled the gap came from a credit union, not a bank. This page covers what Vancity's Multiplex Construction Mortgage offers, what its first six months of numbers say, and where it does not fit.
How Does a Multi-Family Mortgage Work in BC?
CMHC, the federal mortgage insurer, splits multi-family mortgages at four units. A building of 1 to 4 homes where you live in one can get an insured homeowner mortgage if the price is below $1,500,000, with at least 10% down on 3 or 4 units. A rental building of 5 or more homes goes through CMHC's multi-unit insurance, such as MLI Select.
| Rule | 1 or 2 units | 3 or 4 units | 5 or more units |
|---|---|---|---|
| CMHC insurance | Homeowner program: you live in one unit, price below $1,500,000 | Homeowner program: you live in one unit, price below $1,500,000 | MLI Select: at least 5 units, new or existing rental buildings |
| Minimum down payment | 5% of the first $500,000, 10% of the rest | 10% | 5% of cost on a new build; on an existing building 15% at 50 points, 5% at 70 or more |
| Longest amortization | 25 years | 25 years | 40, 45 or 50 years at 50, 70 or 100 points |
| How rent counts | Up to 100% of the gross rent from the other unit is added to your income | Up to 50% of gross rent, or the net rent, is added to your income | The building's own income must cover the loan payments at least 1.10 times (standard rental) |
| A loan to build it | Vancity's Multiplex Construction Mortgage | Vancity's Multiplex Construction Mortgage | Outside the Vancity program (see below) |
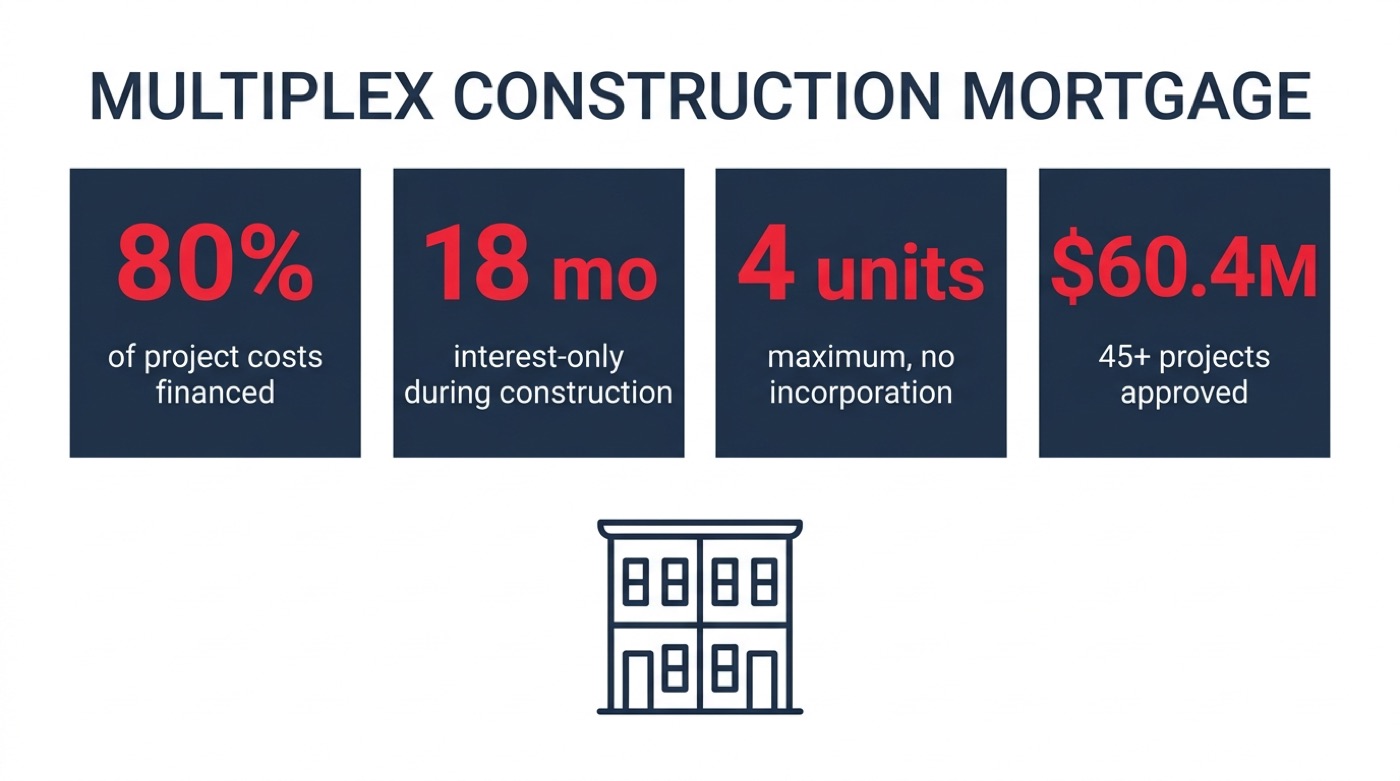
For the homeowner program, your housing costs can be at most 39% of gross income and all your debts at most 44%, both tested at the higher of your contract rate plus 2% or 5.25%. One borrower needs a credit score of at least 600. The insurance premium runs from 0.60% of the loan at 65% loan-to-value or less to 4.00% at 90.01% to 95%. The Financial Consumer Agency of Canada says a buyer with less than 20% down will typically need this insurance. Vancity's construction mortgage covers duplexes, triplexes and fourplexes, lends up to 80% of project costs and charges interest only for up to 18 months while you build.
For MLI Select you need a net worth of at least 25% of the loan, and no less than $100,000, plus five years of experience running similar rental buildings or a contract with a professional property manager. A project needs at least 50 points from affordability, energy or accessibility commitments to qualify.
For the owner-occupied rules in a worked example, see what changes when you live in one unit of your multiplex. For 5 or more units, see how MLI Select points set the down payment and amortization.
Read on November 2, 2026: CMHC's homeowner purchase page, its rental income page (published May 22, 2024), its MLI Select page (published September 21, 2026) and MLI Select at-a-glance sheet (form 66792, 2025); the Financial Consumer Agency of Canada's down payment page; and Vancity's April 8, 2026 release.
Why There Was a Gap at All
A homeowner mortgage funds a finished house in one advance. A commercial construction loan funds a build in stages, but it is underwritten for developers: track record, incorporated borrowers, professional teams. A homeowner replacing their house with a fourplex fits neither box. They need staged draws like a developer and personal, residential-style qualification like a homeowner.
That mismatch is the gap Vancity aimed at. Its October 2025 launch announcement calls the product first-in-market, and the design choices show who it is for: no incorporation required, rental offsets for qualification, and per-co-owner mortgage terms for families and friends building together.
One caution on the label: first-in-market is Vancity's own description. Other lenders finance small multiplexes case by case, and brokers can assemble construction financing from private lenders. What was new here is a named, standardized product a homeowner can apply for directly.
The Program, Term by Term
Up to 80% of project costs
The mortgage advances against the cost of the build, released in stages as construction progresses. You fund the remaining share from equity, and for most homeowners that equity is the lot itself.
Interest-only for up to 18 months
During construction you pay interest only on what has been drawn. The 18-month clock is a real constraint: a build that drifts past it needs a conversation with the lender, so the financing quietly sets the construction schedule.
Up to 4 units, no incorporation
The program covers duplexes, triplexes, and fourplexes on eligible residential lots, held personally. You do not need to set up a company, which keeps the borrowing on the residential side of the bank rather than the commercial side.
Rental offset and co-owner flexibility
Expected rent from the units you will not occupy can support qualification, and where several co-owners hold the property together, each can choose their own term, rate, and amortization on their share.
All terms from Vancity's product page and its launch release. Programs change; confirm current terms with Vancity before planning around them.
Six Months In: What the Numbers Say
October 21, 2025: the product launches
Vancity introduces what it calls a first-in-market Multiplex Construction Mortgage for builds of up to four units on residential lots, initially serving Metro Vancouver, the Fraser Valley, Victoria, Squamish, and Alert Bay.
April 8, 2026: the numbers land
Six months in, Vancity reports more than 45 projects financed, worth a total of $60.4 million plus in approvals, and frames the demand as pent-up: homeowners and small builders who wanted to build multiplexes and had no purpose-built way to borrow for them.
What that average says
Those two published figures put the average approval around $1.3 million per project. That is homeowner scale, not developer scale, which supports what the program was designed for: individual lots, not assembled sites.
Figures from Vancity's April 8, 2026 expansion release. These are the lender's own reported numbers; no independent audit of them exists that we know of.
Where This Instrument Does Not Fit
5 or 6 units
The program caps at four units. A 5-plus-unit rental build belongs in the commercial world with a CMHC MLI Select take-out, which changes amortization, tenure rules, and underwriting entirely.
Partner-funded projects
If a capital partner is funding the build in exchange for profit, the structure lives in the joint-venture financing world, and the JV agreement decides who borrows what.
Outside the service area
The launch named Metro Vancouver, the Fraser Valley, Victoria, Squamish, and Alert Bay. Builders in Kelowna, Kamloops, or Prince George should confirm coverage before counting on the program.
Buying, not building
Purchasing a finished multiplex to live in is a different instrument: a standard mortgage, covered on our owner-occupied financing guide.
Best For
- ✓ Homeowners replacing a single house with up to four units on a lot they already own
- ✓ Families or friends building together who want separate mortgage terms on their shares
- ✓ First-time builders who need residential-style qualification with construction-style draws
Usually Fails When
- ✕ The project is 5 units or more, which is outside the program entirely
- ✕ The build schedule cannot realistically finish inside the 18-month interest-only window
- ✕ The equity share (the roughly 20% of project costs the loan does not cover) is not actually there
What To Verify Before Spending Money
- → Current program terms and service area directly with Vancity, since both have already changed once
- → Your project's unit count and zoning with the address tool below, before any lender meeting
- → Whether expected rents in your area support the rental offset the qualification depends on
Common Questions
How does a multi-family mortgage work in BC? +
CMHC splits it at four units. A building of 1 to 4 homes where you live in one can get an insured homeowner mortgage if the price is below $1,500,000, with at least 5% of the first $500,000 and 10% of the rest down on 1 or 2 units, and 10% down on 3 or 4. A rental building of 5 or more homes goes through CMHC's multi-unit insurance, such as MLI Select, where the building's own income must cover the loan payments at least 1.10 times.
Why did multiplex construction financing come from a credit union first? +
Bill 44 legalized 3 to 6 units on most BC residential lots in 2023, but borrowing to build them stayed awkward: homeowner mortgages are not drawn in construction stages, and commercial construction lending is built for experienced developers. Vancity, a BC credit union, shipped the first product aimed at the gap, calling its October 2025 Multiplex Construction Mortgage first-in-market. Whether other lenders follow is worth watching, but as of mid-2026 this remains the named, purpose-built option for small BC builds.
What does Vancity's Multiplex Construction Mortgage actually offer? +
Per Vancity's published materials: financing of up to 80% of project costs for builds of up to four units (duplex, triplex, fourplex) on eligible residential lots, interest-only payments during construction for up to 18 months, rental offset options to help qualification, flexible terms and amortizations for co-owners, and no requirement to incorporate. Each application is underwritten individually.
How much has the program actually financed? +
Vancity's April 8, 2026 release reports more than 45 projects and $60.4 million plus in approvals since the fall 2025 launch. Those are Vancity's own reported figures.
What if my project is 5 or 6 units? +
The Vancity program caps at four units. At 5 or more rental units the standard path is a commercial construction loan with a CMHC MLI Select insured take-out, which brings its own point-scoring system and a rental-only requirement. The two paths are different enough that unit count should be settled before you approach any lender.
Do I have to be a Vancity member? +
Credit unions lend to members, and Vancity serves members through branches in Metro Vancouver, the Fraser Valley, Squamish, the Sunshine Coast, the Islands, and Alert Bay. Membership requirements and current program terms are questions for Vancity directly; its product page lists [email protected] as the contact.
Related Reading
Official Sources Referenced
See What Your Lot Supports Before You Talk to a Lender
Unit count decides which financing instruments your project can reach. Enter any BC address to see zoning, allowed units, and a preliminary proforma.